
Global investors are heading into the final week of October with plenty to think about. Oil prices remain elevated, tensions in the Middle East continue to raise concerns about energy supplies, and uncertainty over interest rates is making it harder to predict where markets will go next.
Although crude prices have pulled back from recent highs, the underlying concerns have not disappeared. Investors are also preparing for the US Federal Reserve's policy decision and earnings reports from some of the world's largest technology companies. Together, these developments could influence stock markets, bond yields and currencies in the days ahead.
Asian markets traded cautiously on Monday, 26 October, following a difficult week for global equities. Brent crude slipped after reaching a high not seen in nearly six months, with reports of diplomatic efforts to ease regional tensions offering some relief. Even so, investors remain concerned about how prolonged energy disruptions could affect inflation and economic growth.
The combination of higher energy costs and uncertain monetary policy is creating a challenging environment. Expensive oil can push up transport, manufacturing and household expenses, while elevated interest rates make borrowing more costly and can reduce demand for riskier investments.
For companies, this creates a difficult balancing act. Operating expenses may rise just as financing conditions remain tight. Bond investors, meanwhile, are watching closely for signs that persistent inflation could delay interest-rate cuts. Currency markets are also responding to changing expectations about US monetary policy and demand for safer assets.
As a result, investors are becoming more selective. Corporate earnings, cash flow, debt levels and valuations are receiving greater attention as markets try to determine which businesses can withstand another period of uncertainty.
The big question is whether markets can absorb these pressures without a deeper correction, or whether expensive energy and restrictive financial conditions will trigger another bout of widespread volatility.
OIL PRICES — THE BIGGEST SOURCE OF MARKET ANXIETY
Middle East tensions keep energy markets on edge
Oil has become one of the main drivers of investor sentiment as security concerns and shipping disruptions raise questions about the reliability of global energy supplies.
Brent crude climbed approximately 6.2% last week, reaching its highest weekly close since mid-2022 before retreating on Monday. The rally followed reports of Houthi attacks in Saudi Arabia, which heightened concerns about further disruption to energy flows from the Middle East.
The latest pullback has offered some relief, but it has not removed the underlying risks. Traders remain alert to developments around the Strait of Hormuz, one of the world's most important routes for international oil and gas shipments.
If disruptions continue, countries that depend heavily on imported energy could face larger import bills, weaker trade balances and additional inflationary pressure. Airlines, logistics companies, chemical producers and manufacturers could also find it harder to protect their profit margins if fuel and transportation costs remain high.
For investors, the duration of the oil shock matters as much as the price itself. A brief spike may be manageable, but a prolonged period of expensive crude could change expectations for inflation, interest rates and corporate profitability.
Why falling oil prices do not mean the danger is over
Oil prices can fall even when supply risks remain elevated. Traders may respond to diplomatic progress, profit-taking, changing demand expectations or hopes that alternative supplies will become available.
That is why a single day's decline should not be taken as proof that energy markets have stabilised.
Investors will be watching shipping activity, export figures, inventory data and diplomatic developments for clearer signs of whether the recent rally is fading or simply taking a pause.
THE FEDERAL RESERVE — ALL EYES ON INTEREST RATES
The US Federal Reserve's meeting on 27–28 October is another major event shaping market sentiment. The policy decision is expected on Wednesday, 28 October, with investors looking for clues about how policymakers intend to manage persistent inflation.
Economists surveyed by Reuters have generally expected the Fed to leave interest rates unchanged in October, although the possibility of another increase in December remains part of the discussion.
The inflation dilemma
Higher oil prices could make the Fed's job more complicated. Energy costs feed into transportation, production and household budgets, potentially slowing the progress towards lower inflation.
If policymakers believe these pressures will last, they may signal that interest rates need to remain elevated for longer. A more hawkish message than investors expect could push bond yields higher and strengthen the US dollar.
But keeping rates high also carries risks. Expensive borrowing can discourage consumer spending, increase financing costs for businesses and weigh on investment.
Investors will therefore pay close attention to the Fed's statement and the chair's press conference. The key issue is how policymakers balance the risk of persistent inflation against the possibility of weaker economic growth.
Bond yields and the cost of borrowing
Government bond yields matter because they influence borrowing costs across the economy.
When yields rise, bond prices generally fall. Higher yields can also make financing more expensive for businesses and governments, putting pressure on investment plans and company valuations.
Technology and other growth-oriented companies can be particularly sensitive to these changes. When interest rates rise, investors often place a lower present value on profits that businesses expect to earn in the future.
This helps explain why markets can react sharply even when the Fed leaves its benchmark rate unchanged. If policymakers indicate that rates will stay higher for longer, financial conditions can tighten without an immediate rate increase.
WALL STREET — CORPORATE EARNINGS FACE A TOUGHER TEST
US equity markets are entering a busy earnings week, with investors looking for evidence that corporate profits can hold up despite rising energy costs and uncertainty over interest rates.
Results from major technology companies, including Alphabet, Microsoft and Amazon, are among the announcements attracting close attention. Investors will be looking beyond headline revenue figures to assess profit margins, future guidance and spending on artificial intelligence infrastructure.
AI investment comes under closer scrutiny
Artificial intelligence remains a major source of optimism for the technology sector. However, investors increasingly want to see whether the enormous sums being spent on chips, data centres and computing capacity will translate into sustainable returns.
Strong demand alone may not be enough to satisfy the market if infrastructure costs continue to climb. Companies will need to show that their AI investments can support long-term revenue growth and profitability.
Better-than-expected results and confident forecasts could help steady technology shares and support broader market sentiment. Disappointing earnings, on the other hand, could renew concerns about high valuations and whether the current AI investment boom can deliver the returns investors expect.
Investors become more selective
When uncertainty rises, investors tend to look more closely at the financial strength of individual companies.
Businesses with healthy balance sheets, manageable debt and reliable cash flow may be better positioned to handle higher costs than those that depend on cheap borrowing or rapid growth to justify their valuations.
That does not mean financially strong companies are immune to market declines. Even established businesses can see their share prices fall if expectations have become too optimistic.
The broader shift is clear: investors want stronger evidence that companies can deliver consistent results in a more demanding economic environment.
ASIAN MARKETS AND INDIA — EMERGING ECONOMIES UNDER PRESSURE
Asian markets started the week cautiously as investors weighed energy prices, global interest-rate expectations and uncertainty over trade.
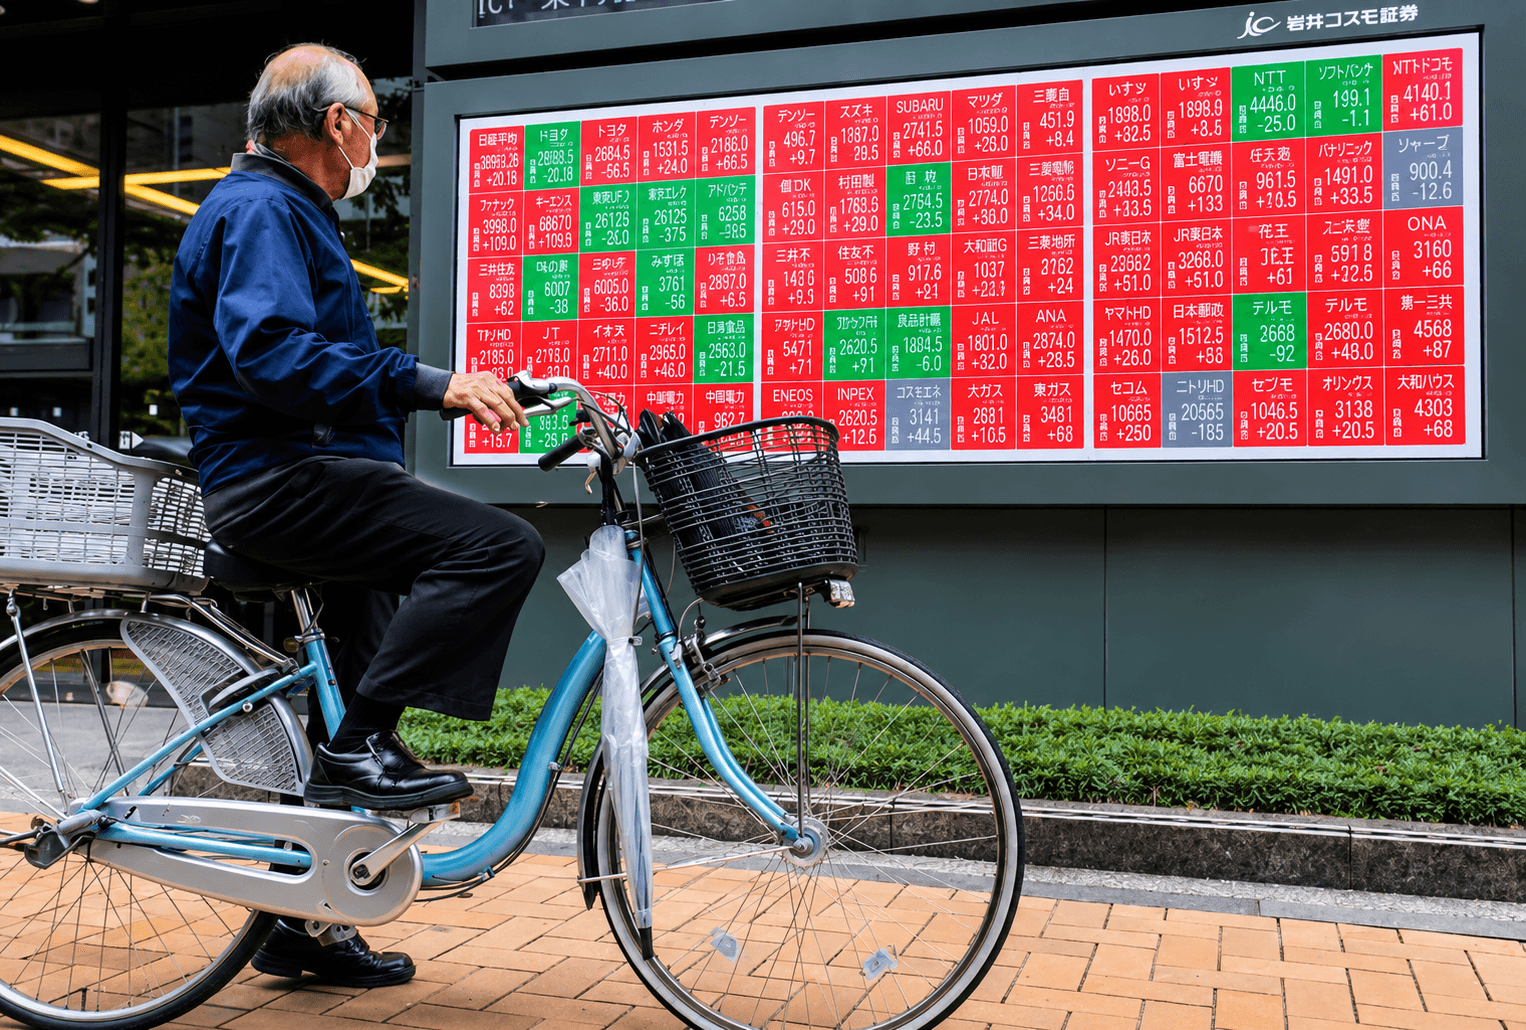
On 26 October, Japan's Nikkei and South Korea's Kospi declined, while Chinese blue-chip shares also weakened. Investors were balancing concerns about energy supplies against upcoming corporate earnings and central-bank decisions.
India faces a difficult combination
Indian equities are particularly sensitive to global crude prices because the country relies heavily on imported oil.
Reuters reported that the Nifty 50 fell 0.5% to 22,485.65, while the Sensex declined 0.46% to 72,783.15 in early trading on 26 October. Concerns over elevated crude prices and the Federal Reserve's upcoming decision weighed on sentiment.
Higher oil prices can increase India's import bill and put pressure on the rupee. A weaker currency can make imported energy even more expensive, adding to inflationary pressures and complicating the outlook for businesses and consumers.
A stronger US dollar and elevated American interest rates can create another challenge. International investors may become less willing to hold emerging-market assets when returns in the United States look more attractive relative to the risks.
Still, India's market outlook is not entirely negative. Domestic consumption, corporate earnings, government policies and investment flows can continue to support individual sectors even when broader sentiment is weak.
What investors are watching in India
Rupee movements: Whether currency weakness adds to the cost of imported goods and energy.
Foreign investment flows: Whether overseas investors increase or reduce their exposure to Indian stocks and bonds.
Corporate earnings: Whether companies can protect profit margins against higher fuel and logistics costs.
Government bond yields: Whether inflation concerns and global rate expectations push borrowing costs higher.
Crude oil prices: Whether a sustained decline eases pressure on India's import bill and external finances.
For Indian investors, the challenge is to determine whether the current volatility is temporary or points to a more lasting deterioration in corporate earnings and economic conditions.
SAFE-HAVEN DEMAND — INVESTORS REASSESS PORTFOLIO RISKS
Uncertainty over inflation, geopolitical tensions and interest rates is prompting investors to reconsider how much risk they want to take.
Government bonds, cash and gold may attract greater interest during periods of market stress, but none offers a guaranteed shield against losses. Bond prices can fall when yields rise, gold can react to changes in real interest rates and the dollar, and cash can lose purchasing power when inflation remains elevated.
The right approach depends on an investor's goals, time horizon, liquidity requirements and ability to withstand losses.
For institutional investors, preserving flexibility is often a priority while the outlook remains unclear. That can mean reviewing exposure to heavily indebted companies, reassessing earnings forecasts and making sure portfolios can withstand sharp moves in interest rates and commodity prices.
The important point is that uncertainty does not push every asset in the same direction. Different markets respond to different pressures, and price movements can change quickly as new information emerges.
WHAT TO WATCH NEXT
Federal Reserve decision — 28 October: Whether policymakers leave rates unchanged and what their guidance suggests about December.
Brent crude: Whether prices continue to retreat from recent highs or rise again on fresh supply concerns.
Middle East developments: Any changes in shipping security, energy exports or diplomatic efforts.
Major technology earnings: Whether Alphabet, Microsoft and Amazon show that their AI investments are translating into sustainable returns.
US Treasury yields: Whether bond markets anticipate interest rates remaining elevated for longer.
Asian stock markets: Whether investors regain confidence or continue reducing exposure to riskier assets.
Indian equities and the rupee: Whether expensive oil and global financial conditions add to pressure on domestic markets.
Inflation and economic growth data: Whether new figures strengthen the case for further rate increases or a more cautious policy approach.
FACT CHECK METER
96% — Strongly supported core reporting
Status: Supported
This is an editorial assessment of the evidence supporting the article's main claims, not an independently calculated probability.
Confirmed details
Global markets traded cautiously on 26 October as investors assessed oil-price movements, central-bank decisions and major corporate earnings.
Brent crude retreated after a strong rally that had taken prices to a level not seen in nearly six months.
The Federal Reserve's policy meeting is scheduled for 27–28 October, with its decision expected on 28 October.
Indian equity benchmarks declined in early trading on 26 October as investors weighed crude prices and the US interest-rate outlook.
Important distinctions
Cautious trading does not necessarily mean a broad market crash is imminent.
Expectations about the Fed's next move are forecasts, not confirmed policy outcomes.
Oil prices can influence inflation and corporate costs, but the impact varies across countries and industries.
Market movements reflect several factors, including earnings, valuations, currency changes and geopolitical developments.
AWX Verdict: Available reporting supports the assessment that investors are approaching the week cautiously as energy-price risks, monetary-policy uncertainty and major corporate earnings converge. Whether these pressures lead to a deeper market correction will depend on the economic data, corporate results and geopolitical developments that emerge over the coming days.
THE AWX BOTTOM LINE
Global investors are dealing with a difficult mix of elevated energy prices, uncertain interest-rate expectations and a demanding technology earnings season. Although crude oil has retreated from its recent peak, concerns about further supply disruptions remain.
The Federal Reserve's upcoming decision could influence bond yields, the dollar and international investment flows. Meanwhile, corporate earnings will test whether businesses can maintain profitability as operating and financing costs remain under pressure.
For India and other emerging markets, the challenge is even more complicated. Higher oil prices can put pressure on currencies and inflation, while global financial conditions may influence the flow of foreign investment. Domestic economic strength will still matter, but international developments are likely to play a significant role in near-term market movements.
The next few trading sessions should offer a clearer picture of whether investors are simply taking a breather after a volatile week or preparing for a more sustained reduction in risk-taking.
For now, caution is setting the tone. The real test is whether resilient corporate earnings and economic activity can offset the pressure from expensive energy and restrictive financial conditions.
ATTLAS NEWS | AWX WORLD NEWS
Real Stories. Lasting Impact.


Comments
No comments yet.