
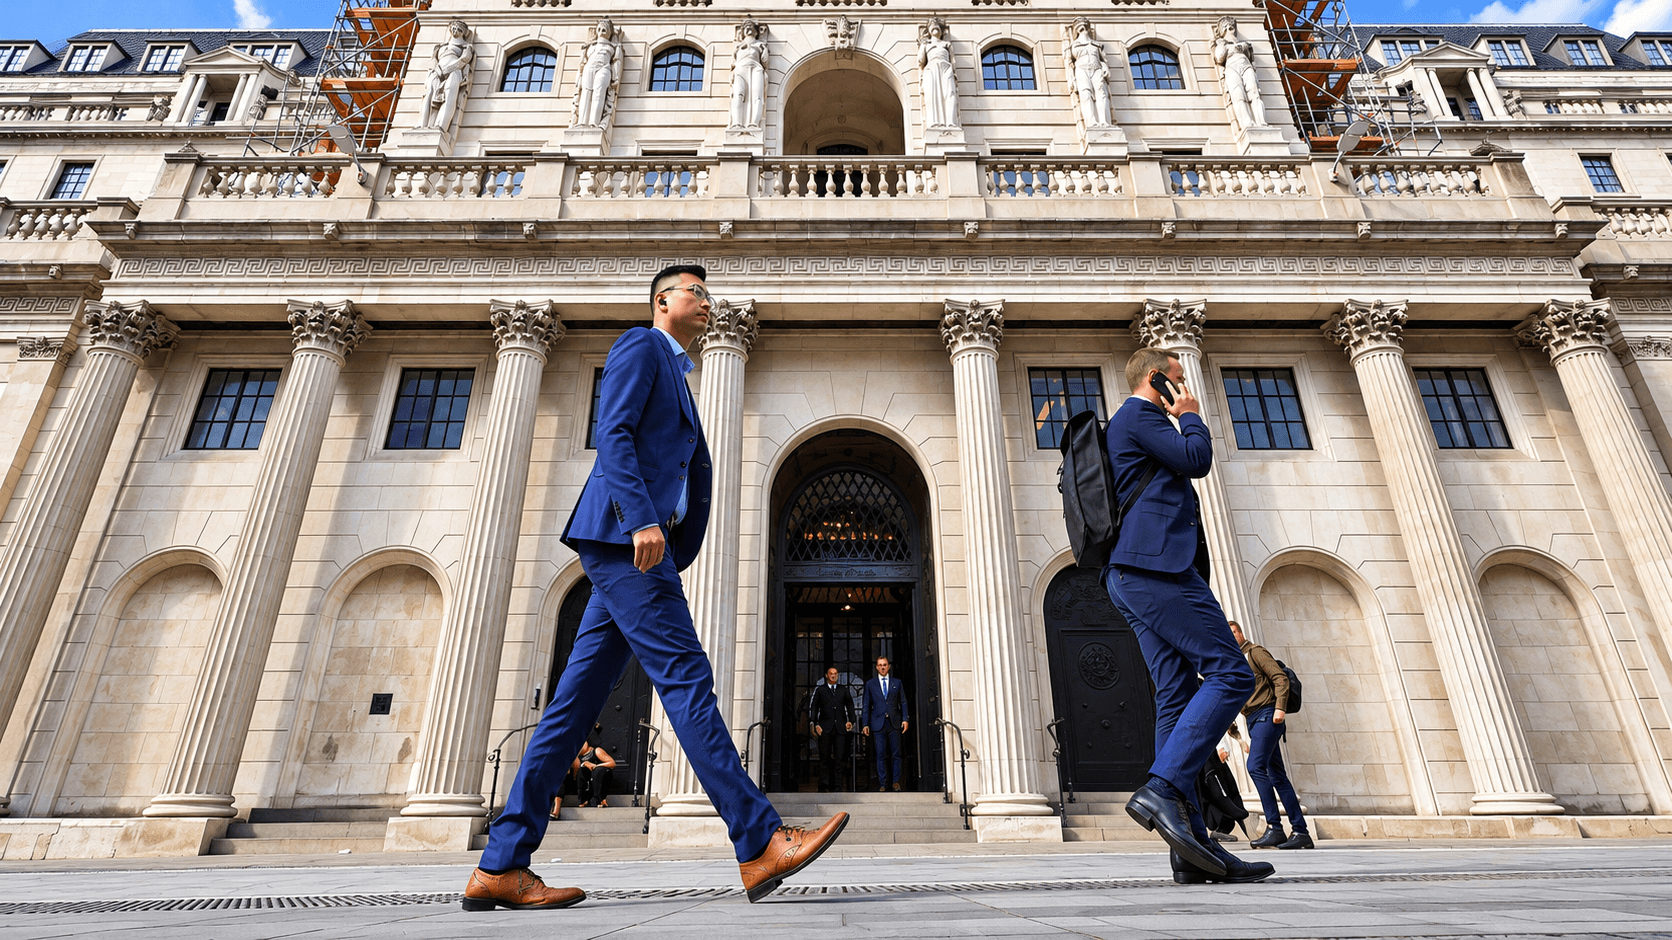
The Bank of England's upcoming interest rate decision is drawing considerable attention from financial markets as rising energy prices threaten to keep inflation above the central bank's 2% target.
The Monetary Policy Committee (MPC) is due to announce its next decision on November 5. Economists surveyed by Reuters broadly expect the Bank to raise its benchmark Bank Rate from 3.75% to 4%. If that happens, it will mark the first increase since August 2023.
The pressure comes after UK inflation climbed to 3.5% in the year to September, above the Bank's earlier forecast of 3%. The prolonged conflict involving Iran and disruptions to energy supplies have added to price pressures, raising concerns that inflation could remain elevated for longer than expected.
Governor Andrew Bailey and other policymakers now face a difficult balancing act. Raising rates could help prevent higher energy costs from triggering further price increases across the economy. However, it would also make borrowing more expensive for households and businesses already struggling with rising living costs.
Thursday's announcement is expected to offer important clues about the direction of UK monetary policy heading into 2027.
RATE HIKE EXPECTED AS INFLATION REMAINS ABOVE TARGET
Markets are increasingly betting on a quarter-point rate increase at Thursday's meeting.
Such a move would take Bank Rate from 3.75% to 4%, reflecting growing concerns that inflation remains well above the central bank's 2% target.
September's inflation figure of 3.5% was higher than the 3% forecast published by the Bank in July. The unexpected increase has strengthened expectations that policymakers may need to act rather than risk allowing inflationary pressures to become more deeply embedded in the economy.
According to a Reuters survey of economists, the MPC could vote 7-2 in favour of raising rates. However, there are still differences within the committee over how much additional tightening the economy can handle.
The Bank has kept interest rates at 3.75% since December 2025, taking a cautious approach while assessing the effects of higher energy prices.
If confirmed, the November increase would mark a notable shift from the rate-cut expectations that dominated market thinking before the escalation of the Middle East conflict.
ENERGY SHOCK AND IRAN CONFLICT ADD TO INFLATION PRESSURE
One of the Bank of England's biggest concerns is how developments in international energy markets are affecting prices across the UK.
The prolonged conflict involving Iran has disrupted energy supplies and increased uncertainty over the transportation of oil and gas. Concerns surrounding the Strait of Hormuz have added another layer of uncertainty to global energy markets.
For British households, higher energy prices can quickly translate into more expensive petrol, electricity and heating bills.
Businesses are also feeling the pressure. Transport operators, manufacturers and other energy-intensive industries face higher operating expenses, some of which could eventually be passed on to consumers.
The Bank is particularly concerned about what economists call second-round inflation effects. This happens when an initial increase in energy prices feeds into higher wages, production costs and the prices of everyday goods and services.
Governor Andrew Bailey has indicated that policymakers cannot afford to wait until all the evidence of these effects becomes clear before considering a response. Delaying action for too long could make inflation harder to bring under control.
At the same time, the Bank must determine whether the current energy shock is temporary or likely to continue putting pressure on prices.
MORTGAGE HOLDERS FACE ANOTHER FINANCIAL CHALLENGE
A further interest rate increase could create additional difficulties for homeowners, particularly those whose fixed-rate mortgage agreements are due to expire.
More than 2.3 million UK households are expected to come off fixed-rate mortgage deals during 2027, according to figures from UK Finance cited by The Guardian. Many could find themselves facing considerably higher monthly repayments when they refinance.
The housing market is already showing signs of pressure. Mortgage approvals fell to a near three-year low in September as higher borrowing costs discouraged potential buyers.
Expectations of further interest rate increases have also pushed up the cost of some fixed-rate mortgage products, even before the Bank has made its latest announcement.
The pressure extends beyond the housing market. The Office for Budget Responsibility has warned that real disposable incomes could decline by 0.6% next year, partly because of rising energy costs.
For families already dealing with higher food, fuel and utility bills, another increase in borrowing costs could make household budgets even tighter.
BANK OF ENGLAND POLICYMAKERS DIVIDED OVER FUTURE RATE PATH
Although markets largely expect an increase in November, there is less agreement among policymakers about how far interest rates may need to rise.
At its September meeting, the MPC voted 6-3 to leave rates unchanged. Some members believe weaker economic activity and spare capacity in the labour market could help bring inflation down without the need for aggressive rate increases.
Others are concerned that prolonged energy price increases could feed into wage demands and business pricing decisions, creating inflation that becomes much harder to reverse.
Reuters has reported that financial markets have been pricing in several additional quarter-point increases during 2027, potentially taking Bank Rate to between 4.75% and 5%.
However, economists remain divided over whether such an aggressive approach will be necessary. Some expect the Bank to signal a more cautious path, even if it decides to raise rates this week.
Investors will pay close attention to the MPC's voting breakdown, the meeting minutes and Andrew Bailey's press conference for clues about what could happen next.
GOVERNMENT COST-OF-LIVING SUPPORT ADDS TO THE POLICY CHALLENGE
The government has also introduced measures aimed at helping households cope with rising energy expenses.
Chancellor John Healey announced a £100 payment for around 20 million households, alongside changes involving fuel duty and electricity bills.
The measures are intended to provide some relief, particularly during the colder months when households typically spend more on heating.
However, the support is unlikely to offset the broader inflationary impact of higher energy prices. Economists cited by Reuters have suggested that the budget measures will have only a limited effect on the overall inflation outlook.
The Bank of England will consider the impact of the government's fiscal decisions alongside its updated economic forecasts.
This leaves policymakers facing a difficult situation. While the government is trying to protect household finances, the central bank may have to make borrowing more expensive to prevent inflation from becoming entrenched.
UK ECONOMIC OUTLOOK FACES GROWING UNCERTAINTY
The upcoming rate decision comes at a time when the UK economy is showing mixed signals.
Economic growth was stronger than expected during the first half of 2026, supported in part by activity in AI-related sectors. However, expectations for the year ahead have weakened as concerns grow that sustained energy costs could affect household spending and business investment.
Higher interest rates may help bring inflation under control, but they also increase financing costs for companies, discourage borrowing and potentially reduce consumer demand.
The Bank must therefore strike a careful balance. Tightening monetary policy too aggressively could put unnecessary pressure on an economy that is already facing several challenges.
The November meeting will include updated forecasts for inflation and economic growth, giving investors a better understanding of how the central bank expects the energy shock to affect the UK.
For households, businesses and financial markets, the key question is whether the Bank can bring inflation under control without pushing the economy towards a deeper slowdown.
RISKS AND KEY ISSUES TO WATCH
Persistent energy inflation: Continued disruption to global oil and gas supplies could keep UK inflation above the Bank's target.
Mortgage affordability: Higher interest rate expectations could increase monthly repayments for households refinancing fixed-rate mortgages.
Wage and price pressures: Rising energy costs could spread into wages and service prices, making inflation more difficult to control.
Economic slowdown: Higher borrowing costs could weaken consumer spending, housing activity and business investment.
Divisions within the MPC: A split vote could reveal significant differences among policymakers over the need for further rate increases.
Government support measures: Budget interventions may ease some household pressure but are unlikely to remove the underlying inflation risks linked to energy prices.
WHAT TO WATCH NEXT
November 5 rate announcement: The Bank of England will announce whether it is raising Bank Rate from 3.75% to 4%.
MPC voting breakdown: The result will show how strongly policymakers support further monetary tightening.
Andrew Bailey's comments: The Governor's press conference could offer important clues about future interest rate decisions.
Updated economic forecasts: New inflation and growth projections will help investors assess the likely direction of monetary policy.
Mortgage market reaction: Banks and lenders may adjust their fixed-rate mortgage products following the announcement.
Energy price movements: Developments in the Middle East and around the Strait of Hormuz will remain important factors in the UK's inflation outlook.
FACT CHECK METER
Editorial confidence: 98%
Strongly supported — Bank of England and Reuters reporting.
Confirmed details
Bank Rate currently stands at 3.75%.
UK inflation reached 3.5% in September 2026.
The Bank's next scheduled rate announcement is November 5.
Energy prices and the Middle East conflict are major concerns for the inflation outlook.
Mortgage holders could face higher refinancing costs.
Important distinctions
The expected increase to 4% is a market forecast, not a confirmed policy decision.
MPC members remain divided over the scale of inflation risks.
Further rate increases in 2027 are not guaranteed.
The longer-term impact of higher energy prices on wages and wider inflation remains uncertain.
AWX VERDICT
The Bank of England is approaching an important monetary policy decision at a particularly difficult time for the UK economy. A rate increase appears likely, but the message policymakers send about future hikes could prove just as important as Thursday's announcement.
The challenge will be to bring inflation under control without placing excessive pressure on households, businesses and economic growth.
The percentage represents AWX editorial confidence in the factual reporting, not a statistical probability or official rating.
THE AWX BOTTOM LINE
The Bank of England faces an increasingly difficult decision as rising energy costs threaten to derail the UK's efforts to control inflation.
Financial markets widely expect Bank Rate to rise from 3.75% to 4% on November 5, reflecting concerns that higher oil and gas prices could push up wages, business expenses and consumer prices.
But the consequences will extend well beyond the financial markets. Homeowners, businesses and ordinary households could face additional financial pressure if borrowing costs rise further.
The November meeting will therefore be an important test of the Bank's ability to balance price stability with economic resilience. Its guidance on the possibility of further increases could be just as significant as the immediate rate decision.
ATTLAS NEWS | AWX WORLD NEWS
Real Stories. Lasting Impact.


Comments
No comments yet.