
Global currency markets are facing another period of uncertainty as investors reassess the outlook for the US dollar following a significant political shift in Washington and changing expectations about economic policy.
The dollar initially weakened after Democrats secured control of both chambers of Congress in the November 3 midterm elections. Investors began considering how the election outcome could affect President Donald Trump's economic agenda, particularly trade policy, government spending and the regulation of major industries.
On November 4, the dollar index dropped 0.6% to 101.27, its lowest level in about a month. The euro climbed to $1.1258, while the Japanese yen and Swiss franc also strengthened against the US currency.
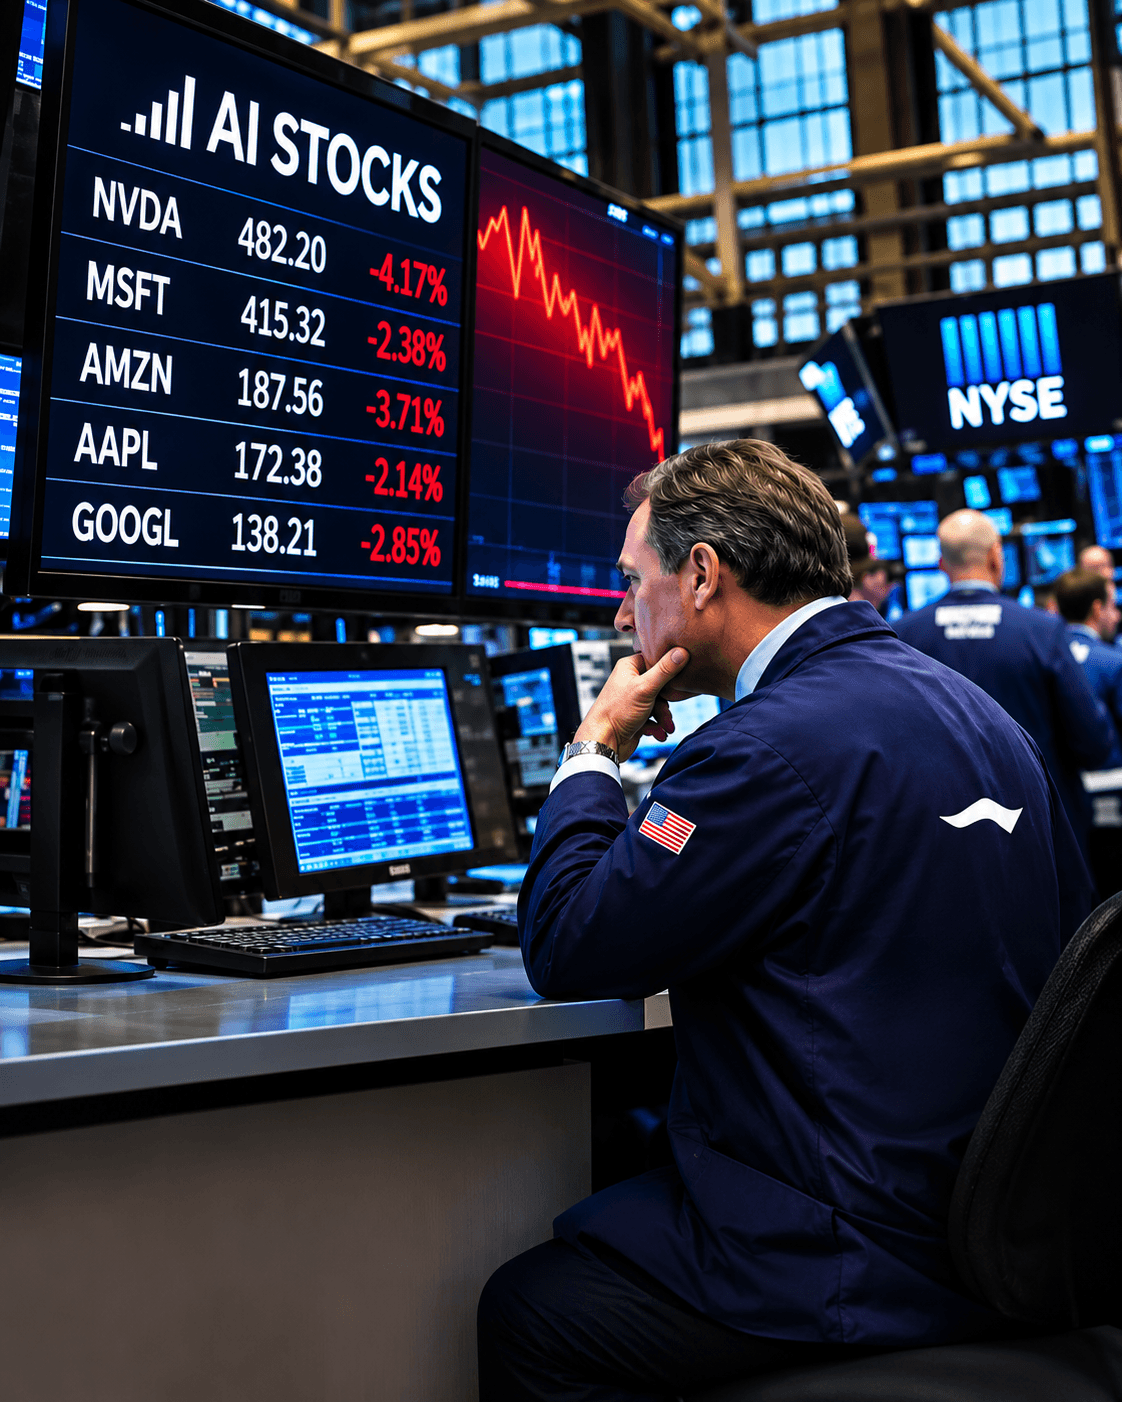
However, the dollar's decline did not last uninterrupted. By November 6, a sharp sell-off in global technology stocks had pushed investors towards safer assets, helping the greenback recover some of its losses. The dollar index rose 0.3% to 101.74 during Asian trading, highlighting how quickly market sentiment can change.
These movements reflect the competing forces currently influencing the dollar. Political uncertainty and lower bond yields are weighing on the currency, while financial market turbulence continues to support demand for liquid, relatively safe assets.
US MIDTERM RESULTS TRIGGER INITIAL DOLLAR DECLINE
The Democrats' midterm victory quickly became a major talking point in currency markets. Investors began examining how a change in congressional control could affect government spending, taxation, trade restrictions and the regulatory environment for major industries.
Concerns about tighter oversight of artificial intelligence also added to market uncertainty. With technology companies facing questions over expensive data-centre projects and future profitability, investors are increasingly cautious about the industry's long-term growth prospects.
According to Reuters reporting, the dollar index slipped to 101.22 on November 5, extending its losses from the previous session. The euro traded around $1.1263, while the yen strengthened to approximately 157.84 against the dollar.
Still, currency analysts warned against treating the initial reaction as a permanent shift in the dollar's direction. Some of the movement may have reflected short-term investor positioning rather than a fundamental change in the currency's long-term outlook.
SAFE-HAVEN DEMAND HELPS THE DOLLAR RECOVER
The sharp decline in global technology shares on November 5 and 6 changed the mood across financial markets.
Heavy selling in US technology and semiconductor stocks prompted investors to reduce exposure to riskier assets and move towards government bonds and currencies traditionally favoured during periods of uncertainty.
The US dollar benefited from this shift, although the Japanese yen also attracted buying interest. On November 6, the yen briefly strengthened to a one-week high of 157.27 per dollar before surrendering some of its gains and trading near 157.80.
Meanwhile, the dollar index advanced 0.3% to 101.74. The euro slipped 0.2% to $1.1198, while the British pound edged lower to around $1.3433.
The latest movements show that the dollar's initial post-election weakness has been partly offset by renewed demand for safe-haven assets. Even amid domestic political uncertainty, the US currency continues to benefit from its position as one of the world's most liquid financial assets.
EURO AND STERLING RESPOND TO CHANGING INTEREST RATE EXPECTATIONS
European currencies have also experienced considerable movement as investors reassess inflation risks and central bank policies.
The euro initially gained against the dollar, supported by falling US Treasury yields and changing expectations about the Federal Reserve's next interest-rate decisions. However, it lost some ground when the greenback recovered during Friday's Asian trading session.
The British pound has been influenced by the Bank of England's November 5 interest-rate decision. The central bank raised its policy rate by 0.25 percentage points to 4%, with eight members supporting the move and one voting against it. Persistent energy-price pressures remain an important concern for policymakers.
Sterling had also benefited from expectations of tighter monetary policy. According to figures reported by The Guardian, the pound reached its strongest level against a basket of currencies since the Brexit referendum in June 2016.
However, higher interest rates do not automatically guarantee a stronger currency. Investors will continue weighing inflation, economic growth, government borrowing and the possibility of further monetary tightening before making longer-term decisions.
FEDERAL RESERVE POLICY REMAINS A KEY MARKET DRIVER
The Federal Reserve's next policy decisions are likely to play a significant role in determining the dollar's direction.
US Treasury yields moved lower as investors sought safer investments following the technology stock sell-off. The two-year Treasury yield fell by approximately 10 basis points overnight, while the 10-year yield also declined before recovering some ground during Asian trading.
Expectations surrounding a possible December Federal Reserve rate increase have also shifted. Reuters reported that futures markets lowered the implied probability of a 25-basis-point increase to around 70%, compared with more than 80% earlier in the week.
The US employment report scheduled for November 6 is another important event for financial markets. Investors are looking for clues about employment conditions, wage growth and the direction of the wider economy.
Stronger-than-expected jobs figures could reinforce expectations of tighter monetary policy and provide fresh support for the dollar. Weaker data, on the other hand, could strengthen the case for a less restrictive approach from the Federal Reserve.
GEOPOLITICAL TENSIONS ADD TO CURRENCY MARKET UNCERTAINTY
Beyond political and economic developments, geopolitical tensions remain another major source of uncertainty for currency traders.
Developments involving the United States, Israel and Iran, particularly concerns surrounding the Strait of Hormuz, continue to influence energy markets and investor confidence.
Movements in oil prices can have a significant impact on inflation expectations and central bank decisions. They also affect currencies differently depending on whether countries are major energy importers or exporters.
The decline in oil prices on November 5 following the US election results briefly improved market sentiment. However, uncertainty surrounding the Middle East remains a potential trigger for sudden movements in commodity prices, bonds and major currencies.
Emerging economies are particularly exposed to these developments. Changes in the dollar's value can affect their borrowing costs, foreign investment flows and the price of essential imports.
EMERGING MARKETS WATCH THE DOLLAR FOR FINANCIAL RELIEF
The dollar's initial weakness offered some relief to emerging economies already dealing with capital outflows and currency pressure.
According to Reuters reporting published on November 5, emerging markets recorded net foreign investment outflows of $33.8 billion in October, the largest monthly withdrawal since March. Taiwan and South Korea were among the markets facing significant investor withdrawals.
A weaker dollar and lower US Treasury yields can make emerging-market investments more attractive. They may also reduce some of the financial pressure on countries and companies with substantial dollar-denominated debt.
However, the dollar's recovery on November 6 suggests that any relief could prove temporary. If investors continue moving towards safer assets, emerging-market currencies may once again come under pressure.
Countries with large external financing requirements and significant foreign-currency debt could be particularly vulnerable if the dollar strengthens further.
RISKS AND KEY ISSUES TO WATCH
1. Dollar volatility: Changing political expectations, falling bond yields and renewed safe-haven demand could lead to further swings in the US currency.
2. Federal Reserve decisions: Upcoming employment and inflation figures could reshape expectations about interest rates and influence the dollar's direction.
3. Japanese yen movements: Differences between US and Japanese monetary policies could create further pressure on the yen and revive concerns about possible currency intervention.
4. European inflation: Energy costs and central bank decisions will remain important factors for the euro and British pound.
5. Emerging-market pressure: A renewed dollar rally could increase borrowing costs and trigger further capital outflows from developing economies.
6. Geopolitical developments: Any escalation in Middle East tensions could cause sudden movements in oil prices, government bonds and major currencies.
WHAT TO WATCH NEXT
1. US employment report: Whether the November 6 jobs figures change expectations for the Federal Reserve's December policy decision.
2. Dollar index: Whether the greenback maintains its recovery above the 101 level or resumes its post-election decline.
3. Bank of Japan policy: Whether expectations of further Japanese interest-rate increases provide additional support to the yen.
4. European central banks: Whether inflation and energy-price pressures influence upcoming decisions by the European Central Bank and Bank of England.
5. Emerging-market currencies: Whether lower US yields and a weaker dollar offer more sustained support to developing economies.
6. Geopolitical developments: Whether tensions involving Iran and the security of the Strait of Hormuz affect energy prices and global currency sentiment.
FACT CHECK METER
Editorial confidence: 98%
Strongly supported — international financial reporting
Confirmed details
The dollar index fell to 101.27 on November 4.
The euro, Japanese yen and Swiss franc initially strengthened against the dollar.
The dollar index recovered to 101.74 on November 6 as safe-haven demand increased.
The Bank of England raised its interest rate to 4% on November 5.
Emerging markets recorded $33.8 billion in net foreign investment outflows during October.
Important distinctions
The dollar's initial decline was followed by a partial recovery. It did not continue falling throughout the period.
Political developments were one factor influencing the currency, alongside Treasury yields, interest-rate expectations and global investor sentiment.
The November 6 US employment report had not yet been released at the time of reporting.
AWX VERDICT
The dollar is facing competing pressures as political uncertainty, shifting interest-rate expectations and global financial volatility pull the currency in different directions.
The Democrats' midterm victory initially weighed on the greenback, but the subsequent technology stock sell-off brought investors back towards safe-haven assets, helping the dollar recover some of its losses.
For now, the currency market is reacting to changing expectations rather than following a clear trend. US economic data, Federal Reserve decisions and developments in global politics will play a major role in determining what happens next.
The 98% figure represents AWX editorial confidence in the article's factual reporting, not a statistical probability or official rating.
THE AWX BOTTOM LINE
Global currency markets are entering a more uncertain phase as political developments, financial market volatility and central bank expectations reshape investor behaviour.
The dollar's initial decline following the Democratic election victory showed how quickly political changes can influence financial markets. Its subsequent recovery, however, highlighted the currency's continuing importance during periods of global uncertainty.
For emerging economies, the dollar's direction remains especially important because it affects external borrowing costs, commodity prices and international investment flows.
The coming days will bring greater clarity as investors assess US economic data, Federal Reserve policy and geopolitical developments. Rather than signalling a straightforward decline in the dollar, recent movements point towards a more volatile currency market where investor confidence can shift quickly.
ATTLAS WIRE | AWX WORLD NEWS
Real Stories. Lasting Impact.
Comments
No comments yet.